
Embedded finance is the practice of building financial services, like payments, loans, insurance or bank accounts, directly into a product that isn’t a bank. You’re probably already using it. The “pay in four installments” button at an online checkout, the debit card a ride-hailing company gives its drivers and the travel insurance offered when you book a flight are all examples.
The idea is simple: instead of sending you to a bank, the app or website you’re already in handles the money part for you. It’s convenient for customers and valuable for businesses, which is why so many platforms have rushed to add it. It also raises real questions about who’s responsible when something goes wrong.
This guide explains what embedded finance is, how it works behind the scenes, seven examples, the benefits and risks and how a business or a curious customer can approach it.
What is embedded finance?
At its simplest, it means a financial service lives inside a non-financial product. McKinsey has noted that more and more nonbank companies are offering bank accounts, wallets, payments and lending, which is the trend behind it. You can read its analysis of embedded finance and banking as a service. The company doesn’t become a bank. It partners with one.
The terms around it get mixed up, so here’s a quick guide.
| Term | What it means |
|---|---|
| Embedded finance | Financial services, like payments, lending or insurance, built into a non-financial product |
| Banking as a service (BaaS) | The model and technology that lets licensed banks offer their services to other companies through APIs |
| Open banking | A way for approved third parties to access a customer’s bank data with consent |
| Sponsor bank | The licensed bank that holds the charter and carries the regulatory responsibility |
A short history: how banking moved behind APIs
For a long time, financial products were sold almost entirely by financial companies. That changed as banks began exposing their systems through APIs and as open banking rules in many countries gave fintechs access to customer banking data. Cloud technology made it cheaper to build on top. Soon a software company could offer a payment account or a loan without becoming a bank.
How does embedded finance work?
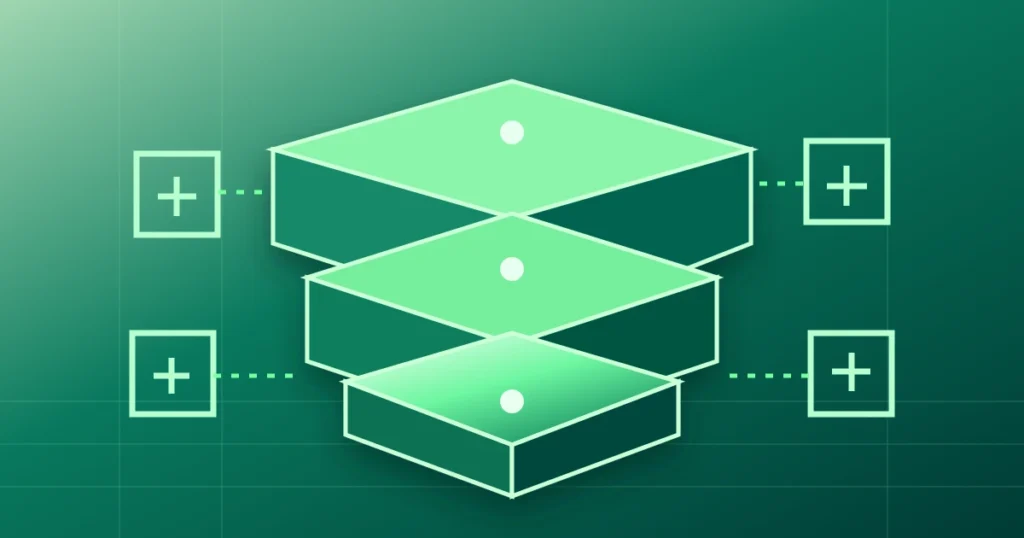
Behind the scenes, it’s usually a stack of three roles connected by APIs, which are the software links that let systems talk to each other. Treasury Prime’s explainer on what is embedded finance describes how APIs connect businesses to banks and fintechs so they can add financial offerings to their core product.
- The platform. The app or brand you actually see, such as a marketplace, a retailer or a software company.
- The BaaS provider. The middle layer that supplies the APIs, technology and compliance tools.
- The sponsor bank. The licensed, regulated bank at the bottom. It holds the charter and legal responsibility for the financial product, and money settles through card networks and payment rails.
Here’s a quick example. When you tap “pay in four” at a checkout, the store’s app calls the provider’s API, which runs the credit and identity checks. A partner bank or lender funds the loan, the store gets paid, and you repay in installments, all without leaving the page.
The economics usually work on distribution. The bank earns on deposits and a share of card fees, the technology provider earns on transactions and the platform earns through loyalty and new revenue.
7 examples of embedded finance
1. Buy now, pay later at checkout
This is the most visible kind of embedded lending. Providers such as Klarna and Affirm let shoppers split a purchase into installments without leaving the store’s checkout page.
2. Payments built into apps
Tap-to-pay wallets and in-app payments, like the saved card in a ride-hailing app, remove the need to enter details each time. The payment is part of the experience, not a separate step.
3. Business banking inside a platform
Shopify Balance gives merchants accounts and debit cards without Shopify being a bank. Behind it sit banking partners and infrastructure from companies such as Stripe.
4. Loans based on your sales
Some platforms offer working-capital loans to sellers using the sales data they already hold. Shopify Capital is a well-known example, issued through partner institutions.
5. Instant payouts and driver cards
Gig platforms often offer workers a debit card or instant payout so they can access earnings right away instead of waiting for a payroll cycle. Uber’s Pro Card for drivers is one example.
6. Embedded insurance
Airlines, travel sites and electronics retailers offer coverage at the point of sale, such as trip protection when you book or device protection when you buy.
7. Financing for big purchases
Car dealers and home-improvement companies increasingly show financing options inside the quote. If you’re comparing solar quotes, our guide to how efficient solar panels are explains what the numbers mean, and you’ll often see loan options sitting right next to the price.
Who benefits?
Customers get convenience: fewer steps, fewer logins and offers that appear at the moment they matter. Platforms gain a new revenue stream and a reason for customers to stay. Banks reach customers they wouldn’t find on their own, and technology providers get demand for their APIs. For small businesses, it can mean getting paid faster or reaching credit based on real sales instead of a long application.
Risks to watch and what to ask
The convenience hides complexity. Regulators have increased scrutiny of partnerships between banks and fintech companies, and sponsor banks carry a lot of responsibility for the companies they work with. Alloy’s guide to understanding embedded finance explains why sponsor banks are liable for risks tied to their fintech partners and why compliance oversight matters.
- Compliance. Identity checks (KYC) and anti-money-laundering rules still apply, even when a platform is the one on screen.
- Third-party risk. If a middleman provider fails, customers can be caught in the middle. The 2024 collapse of the middleware company Synapse left many end users waiting for access to their funds.
- Fraud and data. More platforms handling money means more targets.
- Consumer rules. Lending, payments and insurance each have their own consumer protection rules, which differ between countries.
- Unclear responsibility. It isn’t always obvious which company to contact when something breaks.
How a business can get started
- Pick one use case. Start with a single product, like payments or financing, that fits what your customers already do.
- Choose your partners. You’ll need a BaaS provider and a licensed bank. Check how they handle compliance, and ask about fees, audits and what happens to customer funds if the provider fails.
- Plan for compliance early. Identity checks, fraud monitoring and customer support are part of the job, not extras.
- Design a clear experience. Be upfront about fees, terms and who the partner bank is.
- Measure and expand. Track adoption, losses and complaints before adding more products.
Common mistakes with embedded finance
- Treating it as just a feature. It’s a regulated product with obligations attached.
- Choosing partners on price alone. Oversight and support matter more.
- Hiding the bank. Customers should know who holds their money.
- Launching too much at once. Start small and learn.
- Ignoring customer support. People need a clear place to turn when a payment or loan goes wrong.
Quick answers about embedded finance
Is embedded finance the same as banking as a service? Not exactly. BaaS is the model that makes it possible, and the other is what the customer sees.
Is it safe? It can be, when the partners are licensed and well run. Check who holds your money and what the terms say about protection.
Who regulates it? Sponsor banks are regulated, and consumer protection and anti-money-laundering rules apply. The details vary by country.
Can small businesses use it? Yes, often through ready-made tools from payment processors and lending partners. Starting with one feature is usually easier than building a full banking product.
Does it replace banks? No. Banks still sit behind most programs.
The bottom line on embedded finance
Embedded finance turns everyday apps into places where people can pay, borrow, insure and bank. It’s convenient and commercially powerful, but it works best when the partners are clear about who is responsible. For more explainers like this one, browse the Technology section of The Daily News Point.
This article offers general information and isn’t financial, legal or investment advice. Rules differ by country, so check with a qualified professional before making decisions.
Read More At: TheDailyNewsPoint
Contact Us At: TheDailyNewsPoint
